Market Pulse
The year has been exceptional for equity holders, and November continued the trend with a notable "Trump bump." The Dow Jones Industrial Average climbed an exceptional 7.48%, and the S&P 500 rose 5.62%, as markets responded positively to proposed tax cuts and a strong US dollar following the election. While equities surged on the news, analysts caution that the momentum may face challenges. If the new administration pursues aggressive tariffs, it could spark domestic inflation, undermining the rally. Investors are advised to adopt a wait-and-see approach and avoid rash decisions in either direction.
In contrast to equities, the story in the bond market has been more subdued. Credit risk premiums, as measured by the spread between the 10-year US Treasury yield and corporate bond yields, have hit a cycle low post-election. Tight spreads suggest that corporate bond investors are willing to receive less compensation for risk relative to Treasury bonds. Some fixed-income strategists warn that the corporate credit market may be underpricing risk or not reflecting the heightened uncertainty, potentially signaling a need for caution.
Since the election, the US dollar has embarked on a strong bull run, bolstered by a volatile global economy and potential pro-dollar policies. While technical indicators suggest the dollar may be overvalued in the short term, structural fundamentals remain robust. Proposed tariffs, tax cuts, and deregulation could fuel persistent economic growth, supporting a strong USD over time.
"Green and Clean" investing has faced significant struggles despite the passage of the Inflation Reduction Act, which allocated billions of dollars to renewable energy projects. Challenges such as low-cost competition from Chinese producers, tariffs, insufficient infrastructure, and tight monetary policy have hindered growth in the sector. The new administration's less favorable stance toward green initiatives could further slow progress. However, the long-term trends remain supportive. As renewables achieve cost competitiveness and monetary conditions potentially ease, a recovery in green energy investing could emerge.
The copper market is navigating cyclical headwinds, driven by global growth concerns and adequate supply. Yet, structural tailwinds tied to the green energy transition and data center expansion point to a brighter future. Commodity strategists predict a widening supply-demand deficit by 2026, which could trigger a sustained rally in copper prices. Aluminum markets may also benefit if users increasingly turn to it as a cost-effective alternative to copper. These dynamics underscore the long-term potential in the industrial metals space.
All data sourced from FACTSET and Bloomberg L.P.
All data is for the reported month and in local currency.
The Ups & Downs
- Deere & Company (DE) climbed 15.6% in November. Despite continued YOY revenue declines as we enter a trough in the farming equipment demand cycle, DE continues to maintain margins with effective cost management and strong pricing power.
- Shares of Alimentation Couche-Tard (ATD) re-gained 12.9% in the month. The company reported solid revenue growth in their 2nd quarter despite macro-economic challenges. They posted continual monthly improvement in U.S same-store merchandise revenue.
- Shares of BCE Inc (BCE) declined 15.6% in November. The market reacted poorly to BCE's decision to break into the US fiber market with their acquisition of Ziply Fiber. Analysts would have rathered the company pay down debt instead of the lofty acquisition price.
- Johnson & Johnson (JNJ) declined 3.6% in the month, remaining range bound for the year. The company revised guidance downwards for the year, citing competitive pressures and volume based pricing in China.
All data sourced from FACTSET and SIACharts.
All data is for the reported month and in local currency.
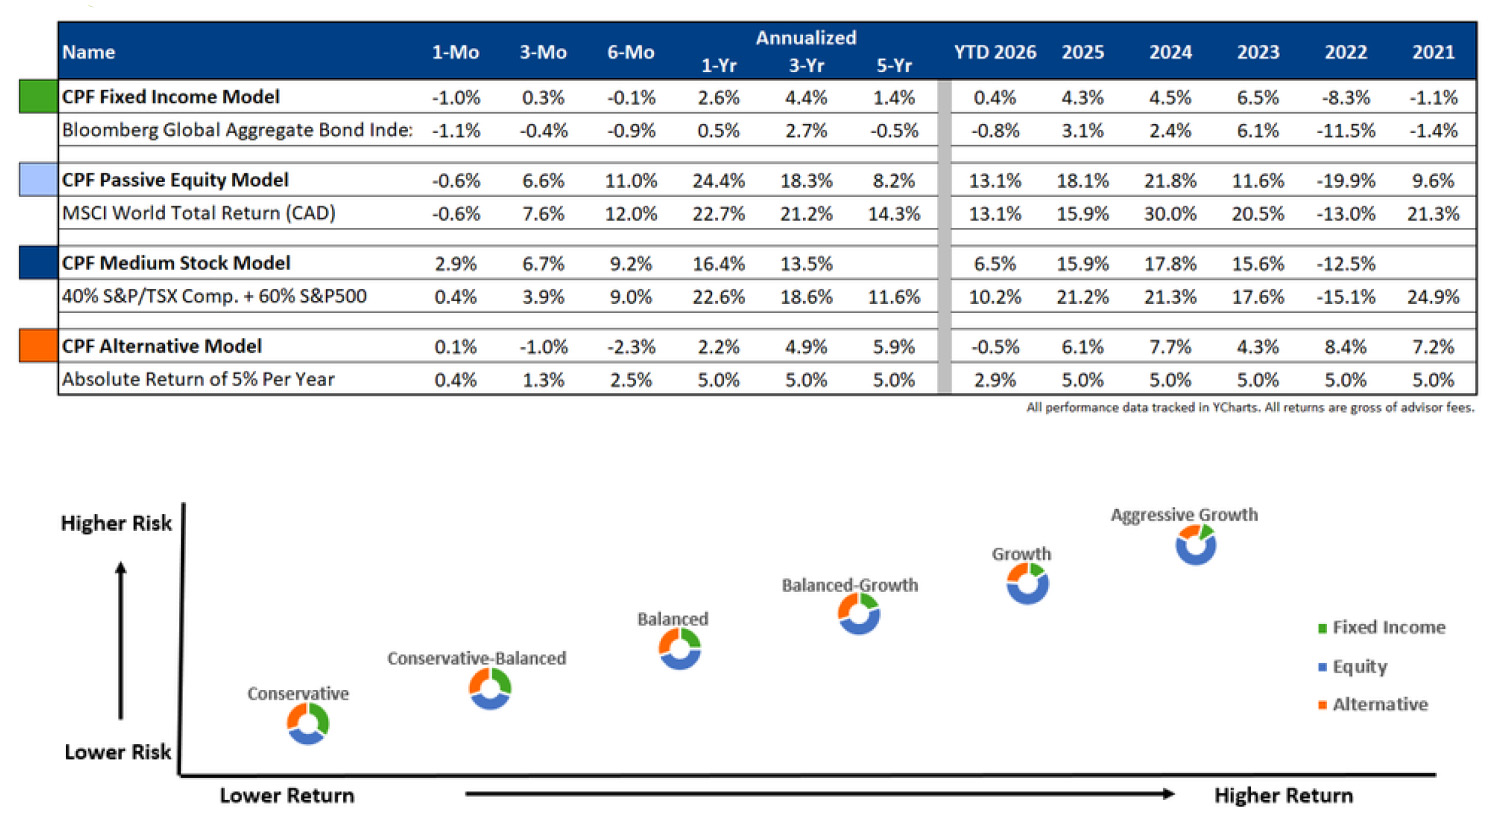
Portfolio Returns
As of November 30th, 2024
Portfolio Highlights
Microsoft (MSFT.TO) surged 24.20% after a blowout fiscal Q4. Revenue of $90.0 billion (up ~18%) and non-GAAP EPS of $4.74 both cleared estimates, driven by the Intelligent Cloud segment as Azure grew 43% and crossed $100 billion in annual revenue for the first time. The result reasserted Microsoft's cloud leadership and eased fears that AI infrastructure costs would erode margins—though it's worth noting the beat was aided by a $3.2 billion gain on its Anthropic stake.
Canadian Natural Resources (CNQ.TO) advanced 19.00%, buoyed by firmer crude prices amid Middle East supply risks and improving sentiment across Canadian energy. The stock drew multiple analyst upgrades, including Zacks lifting it to Strong Buy, while constructive pipeline developments—British Columbia softening its opposition to new pipelines and an Alberta-Ontario proposal for a transcontinental line—added tailwinds. The move reinforced CNQ's standing as a low-cost, capital-disciplined free-cash-flow generator.
TELUS (T.TO) declined 10.80% after a weak Q2 that paired an earnings and revenue miss with a sweeping strategic reset. A C$2.1 billion non-cash impairment at TELUS Digital drove a C$1.8 billion net loss, and the company cut its dividend by 55% while lowering full-year revenue and EBITDA guidance, redirecting capital toward deleveraging. The reset triggered downgrades from Morgan Stanley, CIBC, and Barclays, underscoring the structural and competitive pressures—including Starlink—facing Canadian telecom.
CRH (CRH) fell 8.31% despite a Q2 earnings beat. EPS of $2.21 topped the $2.02 consensus, but full-year 2026 EPS guidance of $5.60–$6.05 landed with a midpoint below the ~$5.95 consensus, and subdued residential construction activity amid high mortgage rates remained a headwind. The pullback reflects investor caution on near-term demand even as infrastructure spending and pricing stay supportive.
All data sourced from FACTSET and Bloomberg L.P.
All data is for the reported month and in local currency.
Macro Watch
In July 2026, the International Monetary Fund released its updated World Economic Outlook, projecting global growth to hold at 3.0% for the year while confirming that global disinflation has essentially stalled. The macroeconomic landscape is becoming increasingly fractured, creating a sharp divide between nations integrated into the booming technology supply chain and those vulnerable to commodity shocks. Policymakers are now navigating an environment where AI-driven demand lifts certain economies, even as prolonged geopolitical conflicts weigh heavily on energy importers.
Energy supply chains remained a volatile focal point throughout the month, significantly altering global inflation trajectories. While a mid-June memorandum of understanding between the U.S. and Iran briefly allowed for the reopening of the Strait of Hormuz, renewed hostilities in July disrupted the gradual recovery of global oil markets. This instability generated a severe supply shock for oil, gas, and fertilizers, ultimately forcing upward revisions in core inflation forecasts and keeping financial markets on high alert.
Despite elevated borrowing costs and global commodity disruptions, the U.S. economy continues to display remarkable resilience compared to its European counterparts. Domestic growth remains steady, heavily supported by massive capital expenditures in artificial intelligence that provide a strong structural floor for business activity. Furthermore, because the U.S. operates as a net energy exporter, its robust consumer sentiment has been largely shielded from the energy price spikes currently suppressing growth in the U.K. and the Eurozone.
All data sourced from FACTSET and SIACharts.
All data is for the reported month and in local currency.
Portfolio Returns
July 2026